 darin
Revenue recognition is the accounting principle that determines when a business can officially record income from sales or services on its financial statements. Rather than simply recording revenue when cash hits your bank account, this principle requires you to recognize income at the specific point when you’ve fulfilled your obligations to the customer, whether that’s delivering a product, completing a service, or meeting another agreed-upon milestone.
For Canadian small business owners, understanding revenue recognition matters because it directly affects how you report income for tax purposes, how investors or lenders evaluate your financial health, and whether your books accurately reflect your business performance. Recording revenue at the wrong time can distort your financial picture, create tax complications, and lead to compliance issues with the Canada Revenue Agency.
Revenue recognition follows IFRS 15, the international accounting standard that Canada uses to govern when and how businesses record income. This standard establishes a five-step process that applies to virtually every type of customer contract, from selling physical products to providing ongoing services. The goal is straightforward: your financial statements should reflect revenue at the moment value transfers to your customer, not simply when payment arrives.
This guide explains what revenue recognition means in practical terms, walks through the five-step process in plain language, and shows how this principle applies to common scenarios Canadian small businesses face every day.
What Revenue Recognition Means for Your Business
Revenue recognition is the accounting principle that tells you when your business can officially record income on the books. It answers a deceptively simple question: when did you actually earn that money? The answer matters because revenue recognition determines the timing of income in your financial statements, which affects everything from your profit margins to your tax obligations.
Here’s the crucial distinction: earning revenue and receiving payment are two different events. You might deliver a service in November but not get paid until January, or you might receive a deposit in March for work you won’t complete until June. Revenue recognition principles guide you through these scenarios by focusing on when you fulfill your obligations to customers, not when cash changes hands.
This timing matters for your financial statements because it determines which accounting period records the income. If you recognize revenue too early, you overstate your current financial performance. Recognize it too late, and you understate your actual business activity. Both scenarios can lead to poor business decisions based on inaccurate data.
The implications extend to tax reporting as well. Proper revenue recognition ensures you report income in the correct tax year, which affects when you owe taxes and helps you stay compliant with Canada Revenue Agency requirements. Getting this right is essential for accurate year-end tax planning and avoiding costly corrections down the road.
How Revenue Recognition Works: The Five-Step Process
Step 1: Identify the Contract with Your Customer
A contract for revenue recognition purposes is any agreement between your business and a customer that creates enforceable rights and obligations. It doesn’t need to be a formal written document, a purchase order, verbal agreement, or even your standard business practice can qualify as a contract.
For a business relationship to trigger revenue recognition, the arrangement must meet specific criteria: both parties have approved the agreement and are committed to fulfilling their obligations, you can identify each party’s rights regarding the goods or services being transferred, payment terms are clear, the contract has commercial substance (meaning your business’s risk or cash flow will change as a result), and it’s probable you’ll collect the payment you’re entitled to receive.
If a customer agreement doesn’t meet all these conditions, for instance, if payment collection is highly uncertain or the contract lacks substance, you can’t recognize revenue yet, even if you’ve received cash.
Step 2: Identify Performance Obligations
A performance obligation is any distinct promise you’ve made to deliver a good or provide a service. For most straightforward transactions, this step is simple: you sell a product, that’s one obligation. But many businesses bundle multiple items together. If you sell software with installation and training, that’s potentially three separate obligations. The key question is whether your customer could benefit from each item on its own or with other resources they already have. If a promised good or service is distinct and separable, it counts as its own performance obligation. This matters because you’ll need to recognize revenue separately as you fulfill each one, rather than recording everything at once when the contract is signed.
Step 3: Determine the Transaction Price
The transaction price is the total amount you expect to receive for fulfilling your obligations, not necessarily what the invoice shows. Start with the stated price, then adjust for variables like discounts, rebates, refunds, credits, or performance bonuses. If a customer earns a 5% discount for early payment and typically pays early, factor that reduction in now. Variable consideration gets tricky: estimate the amount using either the expected value (probability-weighted) or the most likely single outcome, whichever predicts better. Also account for significant financing components, if you’re providing lengthy payment terms that effectively amount to a loan, separate the interest element from the true sale price. The goal is recording what you’ll actually collect for the work performed.
Step 4: Allocate the Price to Performance Obligations
When your contract includes multiple products or services, you need to divide the total price fairly among each performance obligation based on what each item would cost if sold separately. This is called the standalone selling price.
For example, if you sell a computer for $1,200 that includes both the hardware and a one-year software licence, you must determine what each component would sell for on its own. If the computer typically sells for $1,000 and the software licence for $300, you’d allocate the $1,200 proportionally, roughly $923 to the hardware and $277 to the software.
This allocation matters because it affects when you recognize revenue. The hardware revenue is recognized at delivery, while the software revenue spreads across the twelve-month subscription period. Proper allocation ensures your financial statements accurately reflect the value delivered at each stage of the contract.
Step 5: Recognize Revenue When Obligations Are Met
This is the moment when the rubber meets the road, when you can actually record the revenue in your books. You recognize revenue when control transfers to the customer, meaning they can now use and benefit from what you’ve provided.
For a product sale, control typically transfers when the customer receives the goods. For services, it happens as you perform the work, either at completion (like a one-time repair) or progressively over time (like monthly bookkeeping). If you’re delivering multiple items from Step 4, you recognize revenue separately as each piece is fulfilled. A landscaper who quotes $5,000 for design and installation would recognize $1,500 when design plans are delivered and the remaining $3,500 when the work is completed.
The key is matching revenue recognition to actual performance, not to when payment arrives. This ensures your financial statements reflect what you’ve truly earned in a given period.
Common Revenue Recognition Scenarios
The timing of revenue recognition varies dramatically depending on your business model. Understanding when to record revenue in your specific situation helps you maintain accurate books and avoid costly mistakes.
Here are the most common revenue recognition scenarios Canadian small businesses face:
- Immediate product sales where revenue is recognized at the point of sale when the customer takes possession
- Ongoing service agreements where revenue is recognized gradually as services are delivered over time
- Advance payments or deposits where revenue cannot be recognized until you actually deliver the product or service
- Multi-element arrangements that bundle products and services, requiring allocation of the price to each component
- Construction or project-based work where revenue is recognized based on the percentage of completion or specific milestones
A retail store selling clothing recognizes revenue immediately when a customer purchases an item and walks out with it. The transaction is complete, and all five steps of the recognition process happen almost instantaneously.
For service businesses, the timing differs. A landscaping company with a seasonal maintenance contract cannot recognize the full contract value upfront. Instead, revenue is recognized monthly as the service is performed, even if the customer paid the entire amount in advance. The cash is in the bank, but the revenue spreads across the period when you fulfill your obligation.
Subscription models follow a similar pattern. A software company charging annual fees must recognize revenue monthly over the subscription period. Receiving payment in January does not mean you can record twelve months of revenue that month.
Construction and trades businesses face more complex scenarios. A contractor building a custom addition might recognize revenue based on completion milestones or the percentage of work finished. If a project is twenty percent complete, you might recognize twenty percent of the total contract value, assuming that method accurately reflects how you deliver value to the customer.
Multi-element situations require careful allocation. If you sell equipment with a two-year maintenance plan, you must split the total price between the product sale (recognized immediately) and the service component (recognized over two years). Each element gets recognized as its specific obligation is satisfied.
Understanding IFRS 15
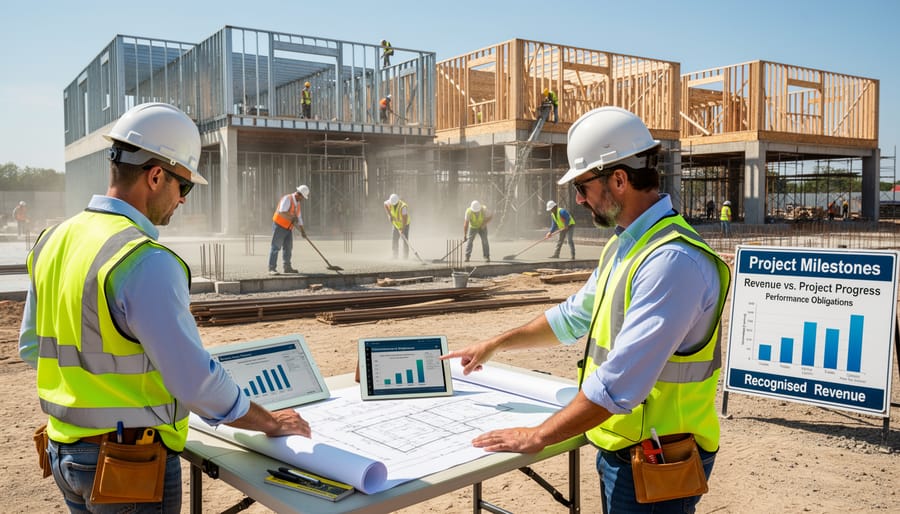
IFRS 15 is the international accounting standard that governs how Canadian businesses recognize revenue from contracts with customers. Adopted in Canada as part of the country’s alignment with international accounting practices, IFRS 15 prescribes one model that applies across all industries and contract types, replacing the patchwork of sector-specific guidance that existed previously.
The standard’s core principle is straightforward: you recognize revenue in a way that depicts the transfer of promised goods or services to customers, in an amount that reflects what you expect to receive in exchange. This means revenue gets recorded when you’ve actually delivered on your promises, not simply when you invoice or receive payment.
- Core principle
- Revenue must reflect the transfer of goods or services in an amount the business expects to receive for those deliverables.
- Performance obligation
- A distinct promise within a contract to transfer a good or service to the customer, which forms the basis for revenue recognition timing.
- Transaction price
- The amount of consideration a business expects to be entitled to in exchange for transferring the promised goods or services.
- Contract modification
- A change in the scope or price of a contract that’s approved by both parties, which may require separate accounting treatment depending on its nature.
For Canadian small businesses, understanding IFRS for small business matters because this unified framework ensures consistency in how revenue is reported across financial statements. Whether you’re selling products, delivering services, or managing subscription contracts, the same five-step model applies, making it easier to maintain accurate books and meet reporting requirements without navigating industry-specific exceptions.
Why Proper Revenue Recognition Matters
Getting revenue recognition right isn’t just about following rules, it’s about protecting and growing your business. When you record revenue at the proper time, your financial statements accurately reflect your company’s performance, which matters whether you’re reviewing monthly reports or preparing year-end taxes.
Tax compliance depends on correct timing. Recording revenue too early or too late can trigger auditing issues, penalties, or unexpected tax bills. The Canada Revenue Agency expects your income reporting to align with accepted accounting principles, and discrepancies raise red flags.
Accurate revenue recognition also affects your ability to secure financing. Banks and lenders scrutinize your financial statements when considering loans or lines of credit. If your revenue figures don’t reflect the true state of your business, you may struggle to qualify for the funding you need to expand or manage cash flow.
Perhaps most importantly, proper recognition helps you make better business decisions. You can’t evaluate profitability, forecast cash flow, or plan growth if your revenue numbers are skewed. Understanding what you’ve truly earned versus what you’ve simply invoiced gives you clarity on your financial position.
Family Business Services’ national network of bookkeeping professionals helps Canadian small businesses apply revenue recognition principles correctly, ensuring your financial records support both compliance and confident decision-making.
How Revenue Recognition Is Used
Revenue recognition principles shape critical business activities every day. Business owners use these rules to prepare accurate financial statements that reflect their company’s true performance, which investors, lenders, and potential buyers review when making decisions. Your monthly or quarterly financial reports rely on proper revenue recognition to show whether you’re genuinely profitable or simply collecting cash that belongs to future periods.
The framework guides day-to-day operational decisions. When you negotiate contract terms with customers, understanding when you can recognize revenue helps you structure payment schedules and delivery timelines that align with your cash flow needs while maintaining compliant records. Service businesses use these principles to determine billing practices, deciding whether to invoice upon contract signing, at project milestones, or after completion.
Tax preparation depends heavily on accurate revenue recognition. Your business’s taxable income calculation starts with properly recognized revenue, making these principles essential for filing returns and planning tax obligations. Modern accounting software builds revenue recognition rules into automated workflows, reducing errors and ensuring your books reflect when you’ve actually earned income rather than just when money changes hands.
Business owners also apply revenue recognition when evaluating performance trends, setting realistic sales targets, and making strategic decisions about pricing or expansion.
Common Questions About Revenue Recognition
Do not include the section title in your output; start directly with the content.
Revenue recognition can feel confusing when you’re managing day-to-day bookkeeping, so let’s address the questions most Canadian small business owners ask.
When do I recognize revenue versus when I get paid?
You recognize revenue when you fulfill your obligation to the customer, when you deliver the product or complete the service, not necessarily when payment arrives. Payment timing and revenue recognition are separate accounting events.
Do I need to follow IFRS 15 as a small business?
IFRS 15 applies to businesses preparing financial statements under international accounting standards in Canada. Many small businesses use simpler methods for internal bookkeeping, but the underlying principles still guide proper revenue timing.
How does revenue recognition affect my taxes?
The timing of when you recognize revenue directly impacts your taxable income for that period. Recognizing revenue correctly ensures you’re reporting income in the right tax year and avoiding compliance issues with the CRA.
What if I receive payment in advance?
Advance payments create a liability on your books until you actually deliver the goods or services. You recognize the revenue only when you fulfill your performance obligation, not when the cash hits your account.
If these distinctions feel overwhelming, you’re not alone. Working with a financial consultant through Family Business Services ensures your bookkeeping reflects the right revenue timing without the headache of interpreting accounting standards yourself.
Getting revenue recognition right isn’t just about following accounting rules, it’s about understanding the true financial health of your business and making decisions based on accurate information. When you recognize revenue at the appropriate time, you gain a clearer picture of your cash flow, profitability, and growth trajectory. This clarity becomes essential when you’re planning for expansion, applying for financing, or preparing for tax season.
For many Canadian small business owners, navigating IFRS 15 and its five-step process can feel overwhelming alongside the daily demands of running a business. That’s where professional support makes the difference. Family Business Services offers affordable bookkeeping and expert tax advice through a national network of professionals who understand the unique challenges small businesses face. With the right guidance, you can ensure compliance, avoid costly mistakes, and free up your time to focus on what you do best, growing your business.