 darin
Most Canadian family businesses should consider incorporation when annual profits consistently exceed $50,000 to $70,000, though the exact threshold depends on your province’s tax structure and your personal financial situation. Below this range, administrative costs and complexity often outweigh the tax benefits. Above it, the corporate tax structure typically begins to deliver meaningful savings.
The timing decision hinges primarily on the gap between personal and corporate tax rates. Corporations are subject to corporate tax rates that are generally lower than personal rates at higher income levels, creating an opportunity to retain and reinvest earnings inside the corporation rather than drawing them personally. This advantage grows as your business income rises, but it comes with trade-offs including setup costs, ongoing compliance requirements, and the potential for double taxation when profits are eventually distributed to shareholders as dividends.
Beyond the numbers, timing factors include liability protection needs, estate planning goals, and the ability to income split with family members who work in the business. A construction company facing project risk calculates differently than a retail shop with stable cash flow. Farmers approaching succession planning may prioritize different features than young tradespeople building their first crews.
This guide walks you through the specific timing windows when incorporation makes financial sense, the non-financial factors that can shift your decision earlier or later, when to seek professional advice, and what to expect after you incorporate. The goal is clear guidance on whether you’re ready now or should wait.
The Quick Answer: Three Signs It’s Time to Incorporate
Most Canadian family business owners don’t need to guess about incorporation timing. Three concrete signals tell you when it’s time to have that conversation with your accountant.
First, your business regularly generates profits beyond your immediate personal income needs. When you’re earning more than you withdraw for living expenses, corporate structure lets you hold those profits in the business where they face different tax treatment. This becomes particularly relevant during year-end tax planning when you’re reviewing annual profitability.
Second, your liability exposure has increased as you’ve grown. Contractors taking on larger projects, farmers operating heavy equipment, or service providers working directly in clients’ homes all face situations where personal assets could be at risk. Incorporation creates a legal separation between business obligations and your family’s personal property.
Third, you’re thinking about the next generation. If you want your children to eventually take over, or you’re considering semi-retirement while keeping ownership stakes, incorporation makes those transitions far smoother. Transferring shares of a corporation is simpler than unwinding a sole proprietorship or partnership.
You don’t need all three signals to justify incorporation. Even one strong indicator deserves professional attention. The mistake isn’t incorporating too early; it’s waiting until a problem forces your hand when strategic timing would have given you better options.
Understanding What Incorporation Actually Changes
When you incorporate, you create a legal entity completely separate from yourself. Your business stops being an extension of you personally and becomes its own “person” in the eyes of Canadian law. This shift carries real consequences for how your business pays tax, who’s responsible for debts, and how you access your profits.
As a sole proprietor or partner, your business income flows directly onto your personal tax return. You and the business are legally one. Once incorporated, the corporation files its own tax return and pays corporate tax on profits. You become a shareholder (and often an employee), which means you can only access profits by paying yourself a salary or taking dividends, both of which create personal tax obligations.
- Corporation vs. Sole Proprietor
- A sole proprietor operates as an individual with no legal separation between personal and business affairs. A corporation is a distinct legal entity that exists independently of its owners, with its own tax obligations and liability.
- Canadian-Controlled Private Corporation (CCPC)
- A corporation owned and controlled by Canadian residents that qualifies for specific tax treatments. Most family businesses operate as CCPCs to access small business tax advantages.
- Qualified Small Business Corporation
- A CCPC meeting specific criteria, including total assets under the CCPC asset and limit of $50 million and no more than 500 employees. This status unlocks capital gains exemptions when selling shares.
- Double Taxation
- The concept that corporate profits face tax twice: first at the corporate level when earned, then again when distributed to shareholders as dividends. This corporate double taxation structure means planning how you withdraw profits becomes essential.
The double taxation reality deserves attention. Your corporation earns $100,000 in profit and pays corporate tax (the rate depends on your province and whether you qualify for small business treatment). What remains after corporate tax sits inside the company until you decide to take it out, either as salary (which reduces corporate taxable income but creates personal income tax) or dividends (which don’t reduce corporate tax but may qualify for dividend tax credits that partially offset the double taxation).
This structure isn’t necessarily worse than sole proprietorship. Done properly, it can lower your overall tax burden, especially if you don’t need all profits immediately for living expenses.
Critical Timing Windows: When Incorporation Makes Financial Sense
Revenue and Profit Considerations
The profitability question centers on whether the corporate structure reduces your total tax burden compared to reporting all income personally. When you remain unincorporated, business profits flow directly onto your personal tax return and get taxed at personal income rates. As a corporation, profits face corporate tax rates first, then additional taxation when you draw money out as salary or dividends.
The advantage emerges when you don’t need to extract all profits immediately. If your business earns more than you need to live on, the portion left in the corporation gets taxed at corporate rates, which can be lower than the top personal marginal rate you’d pay on the same income. That gap creates opportunity to defer tax, reinvest retained earnings, or plan distributions across multiple years to smooth personal income.
The calculation depends on your personal tax situation, planned withdrawals, and future income projections. A farm operation netting steady profits might benefit immediately, while a startup with inconsistent earnings may find the compliance costs outweigh any tax advantage. Your accountant can model both scenarios using your actual numbers to show whether incorporation saves you money now or sets you up for future efficiency as profits grow.
Family Income-Splitting Opportunities
Incorporation creates opportunities for family businesses to distribute income among multiple family members who genuinely contribute to the operation. When family members hold shares or work in the business, you can pay them dividends or reasonable salaries based on their actual involvement. This spreads income across several individuals rather than concentrating it all with one owner.
The tax advantage comes from utilizing each family member’s personal tax situation. A spouse who manages bookkeeping, children who help with operations during busy seasons, or a retiring parent who provides advisory services can receive appropriate compensation for their real contributions. This approach works best when each person legitimately participates in the business and receives payment that reflects the value of their work.
However, Canada’s tax rules require that compensation must be reasonable for the services provided. You cannot simply assign income to family members who have no actual role. The CRA scrutinizes these arrangements, particularly payments to spouses and adult children, to ensure they represent genuine business activities. Your accountant can help structure family involvement in ways that provide tax efficiency while meeting compliance requirements.
Factors That Shift Your Incorporation Timeline
Liability Protection Needs
Personal liability exposure changes dramatically based on how your business operates. Contractors working on client properties face potential claims if something goes wrong during a project. Farmers using heavy equipment or hosting visitors carry different risks than home-based consultants. Service providers giving professional advice might face liability that product retailers don’t encounter.
As a sole proprietor or partnership, your personal assets, your home, savings, vehicles, stand exposed to business claims and creditor actions. A lawsuit or unpaid supplier could pursue everything you own personally.
Incorporation creates a legal separation. The corporation owns the business assets and assumes the business liabilities. Your personal property sits outside that corporate entity, shielded from most business-related claims. This protection doesn’t cover personal guarantees you sign or fraudulent actions, but it separates routine business risk from your family’s financial security.
For high-risk operations, construction, farming with significant equipment, manufacturing, this protection makes incorporation timing urgent rather than optional.
Succession and Estate Planning Goals
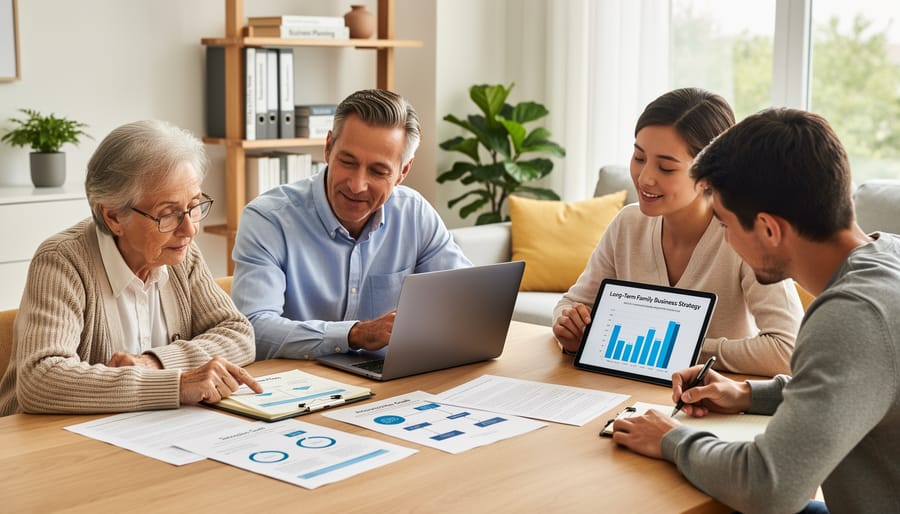
If you’re building a business you hope to pass on, incorporation creates the framework for a smooth transition long before you’re ready to step back. Transferring shares in a corporation is simpler and more tax-efficient than selling or gifting the assets of an unincorporated business. You can gradually transfer ownership to the next generation over time, bringing adult children or family members on as shareholders while you continue to manage operations.
Incorporation also gives you flexibility in structuring ownership. You might allocate different classes of shares to different family members based on their involvement and future roles, or set up a family trust to hold shares and distribute income across generations. These options are only available once the business is incorporated as a distinct legal entity.
If family continuity is a priority, incorporating earlier rather than later makes planning easier. It establishes the corporate structure when the business is simpler, before asset values grow and transitions become more complex. Waiting until retirement is near can create rushed decisions and missed planning opportunities, whereas incorporating during your active years lets you shape ownership transitions on your timeline.
Administrative Readiness
Incorporation brings ongoing administrative obligations that demand reliable systems and processes. You’ll need accurate monthly bookkeeping to track corporate income and expenses separately from personal finances, prepare quarterly financial statements for tax planning, and maintain corporate minute books documenting all shareholder and director decisions.
Payroll becomes more complex when owners become employees of their corporation. You’ll file separate remittance returns, withhold and remit source deductions, issue T4 slips annually, and maintain payroll records for CRA review. Many family businesses find that accounting payroll software streamlines these tasks and reduces compliance errors.
Corporate record-keeping extends beyond basic bookkeeping. You must file corporate tax returns annually, maintain proper documentation for shareholder transactions, keep contracts and agreements organized, and preserve records for the CRA’s required retention periods.
Before incorporating, assess whether you have the capacity to handle these demands in-house or budget for professional bookkeeping support. If your current record-keeping is sporadic or informal, strengthen those systems first. The administrative burden of corporate status is manageable with the right tools and support, but it shouldn’t catch you unprepared.
Working with Your Accountant: Getting the Timing Right
Making the incorporation decision without professional input is a gamble no family business owner should take. Your accountant or financial consultant sees your complete financial picture and can model what incorporation means for your specific tax situation, both now and as your business grows. They’ll compare corporate and personal tax treatment based on your current revenue, projected profits, and family income-splitting goals, giving you concrete numbers instead of guesswork.
Before meeting your accountant, gather three years of financial statements, current revenue projections, and a clear explanation of your business goals (growth plans, succession timeline, liability concerns). The CRA guide for small businesses provides foundational information on obligations, record-keeping requirements, and tax planning considerations that help you understand what questions to ask. This preparation makes your consultation more productive and ensures nothing critical gets overlooked.
Family Business Services connects Canadian small business owners with experienced professionals across the country who understand the incorporation decision for family operations. Our national network delivers affordable, expert guidance tailored to your business stage, whether you’re a contractor evaluating liability protection, a farmer planning succession, or a service provider hitting revenue thresholds where corporate structure makes sense. Getting the timing right means working with someone who knows your industry, your province’s specific requirements, and the tax implications that matter to your family’s financial future.
What Happens After You Incorporate: First-Year Essentials
The first year as a corporation brings new responsibilities that unincorporated businesses don’t face. You’ll need to establish systems and habits now to keep your corporation in good standing, and avoid surprises at year-end.
Start by completing these essential tasks in order:
- Register your corporation officially with your provincial registry and obtain a business number from the CRA.
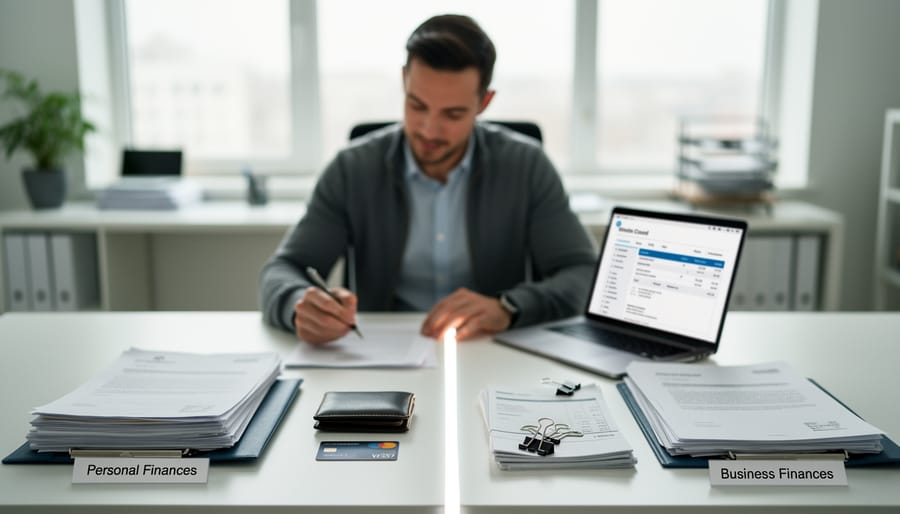
- Open a dedicated corporate bank account, keeping it completely separate from personal finances, no mixing transactions.
- Set up corporate bookkeeping from day one, tracking all income and expenses under the corporation’s name.
- Establish payroll if you’re now an employee of your own corporation, which may require tools like QuickBooks payroll to manage regular pay cycles and remittances.
- File your first corporate tax return within six months of your fiscal year-end, even if the corporation had minimal activity.
- Maintain a corporate minute book with all resolutions, share certificates, and director meeting records.
The separation between you and the corporation is absolute. Every dollar moving between the business and your personal accounts must be documented as salary, dividends, shareholder loans, or repayments. Treat the corporation as a distinct entity in all financial dealings, that legal separation only protects you if you respect it consistently.
Corporate record-keeping goes beyond tracking income and expenses. You’ll need contemporaneous documentation for director decisions, shareholder resolutions, and any major business actions. Keep meeting minutes even when you’re the sole director, and update your minute book whenever you issue shares or make structural changes. These records prove your corporation operates legitimately as a separate entity, which becomes critical during audits or if liability protection is ever tested.
Common Incorporation Timing Questions
Many Canadian small business owners grapple with similar questions when considering incorporation. Here are answers to the most frequent timing concerns we hear from family businesses across the country.
Can I incorporate before I start earning revenue?
Yes, you can incorporate at any stage, even before generating income. Some business owners incorporate early to secure their business name, establish credibility with potential clients, or prepare for grant applications that require corporate status. However, you’ll face ongoing administrative costs and compliance requirements regardless of revenue, so weigh these expenses against your immediate needs.
Should I wait until I reach a specific income level?
There’s no universal income threshold that triggers incorporation. The decision depends on your total tax situation, including other family income sources, your industry’s liability exposure, and your growth trajectory. Working with an accountant helps you model whether corporate tax treatment would reduce your overall tax burden at your current and projected income levels.
What if my business has seasonal income fluctuations?
Seasonal businesses can actually benefit from incorporation because the structure lets you retain profits in the corporation during high-earning periods and distribute income more evenly throughout the year. This income smoothing can help manage your personal tax bracket, though you’ll need solid cash flow planning to handle corporate obligations during slower months.
Can I reverse the decision if incorporation doesn’t work out?
While technically possible to dissolve a corporation or convert back to sole proprietorship, the process involves professional fees, potential tax consequences, and administrative complexity. Treat incorporation as a long-term structural decision rather than a trial arrangement you can easily undo.
How long does the incorporation process typically take?
Federal incorporation can be completed in one to three business days for online applications, while provincial incorporation timelines vary by jurisdiction. However, the legal registration is just the first step, setting up corporate banking, transferring assets, adjusting contracts, and establishing proper bookkeeping systems can take several additional weeks.
The answers to these questions reinforce an important principle: incorporation timing is highly individual. Your accountant can help you assess whether your specific circumstances justify making the change now or waiting until your business reaches a different stage.
Deciding when to incorporate isn’t about hitting a magic revenue number, it’s a strategic choice shaped by your business’s financial trajectory, liability exposure, succession goals, and operational capacity. The factors outlined here give you a framework to assess whether now is the right time or if waiting makes more sense for your situation.
This decision carries real consequences for how you’ll pay taxes, protect assets, and eventually transition ownership. Don’t make it in isolation. Talk to an accountant who understands Canadian family businesses and can run the numbers based on your actual circumstances.
Our national network connects you with experienced professionals who specialize in guiding small business owners through incorporation decisions at rates that won’t strain your budget. Whether you’re ready to move forward or still evaluating your options, getting expert input now helps you time this transition right and avoid costly missteps down the road.